Lime Crosses $1 Billion Revenue Mark as Fleet Growth Outpaces Margin Pressure
Lime has broken the $1 billion barrier in trailing twelve-month revenue — a first for the shared micromobility operator. The milestone lands alongside a Q3 2026 report that shows revenue climbing to **$361 million, up 20% year-on-year**.
Net income moved faster still. Lime booked $44 million in profit for the quarter, a 41% jump, pushing its net margin to just over 12%. A year ago, that figure sat at 10.3%.
The fleet does the heavy lifting
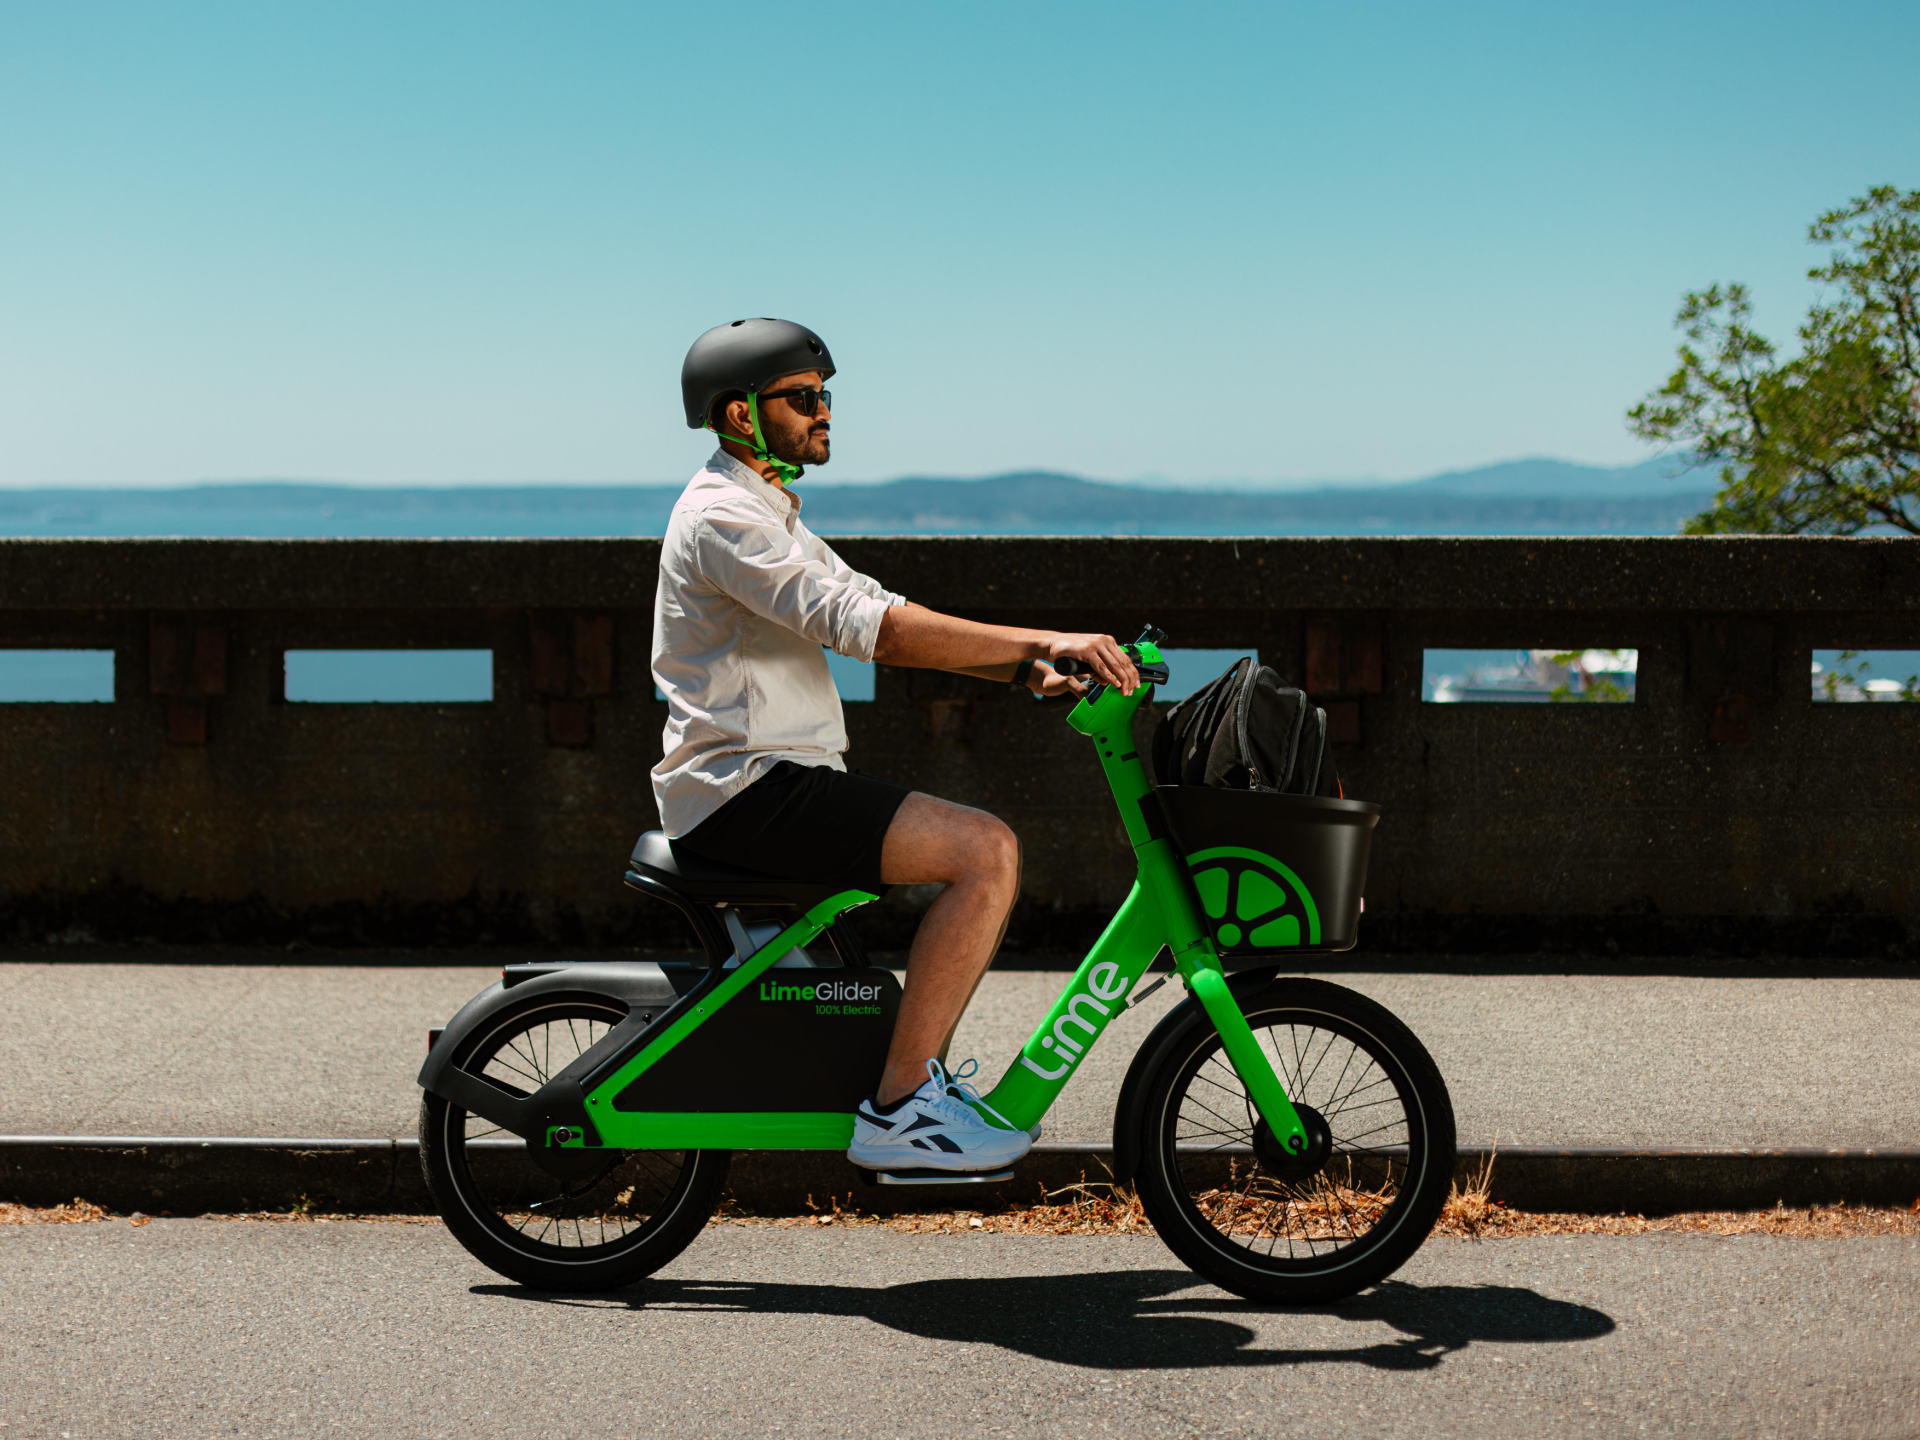
CEO Wayne Ting credited the topline to “strong fleet growth and positive rider retention trends” during the company’s earnings call. The numbers back him up: Lime’s average operational fleet reached 447,000 vehicles in Q3, a 26% increase over the same period last year.
That pace is quicker than what Lime managed in Q2, and Ting framed it as proof there is still room to grow. Existing markets can absorb more vehicles, he said, and several new cities could benefit from the service.
Q3 2026 In Brief: $361M revenue (+20% YoY) · $44M net income (+41%) · 447,000 average operational fleet · 5.5M monthly active users
The picture gets less comfortable further down the income statement. Adjusted EBITDA rose 11% to $118 million, but the margin slipped from 35.4% to 32.8%. Underlying earnings are still growing — just not as quickly as revenue.
Why riders are paying less per day
A key culprit: Revenue per Vehicle per Day fell 4.8% year-on-year to $8.77.
Ting pointed to expansion into what he called “newer mega-markets” such as Australia. In fresh territory, Lime has to establish fleet reliability before demand shows up, so RVD tends to start low and climb over time.
LimePrime, the company’s monthly subscription with unlimited unlocks and flat-rate pricing, is the second factor. Flat rates sit below pay-as-you-go pricing, so the average price point drops as more riders sign up. Ting isn’t worried — he said subscribers take eight times as many trips as non-subscribers, and that the trade-off pays off in retention and lifetime value.
The third pressure point is competition, mostly in Europe. Ting said “recent competitive behavior” weighed on both RVD and monthly active user growth, though MAUs still rose 16% to 5.5 million.
Cash burn and a cautious forecast
Free cash flow in Q3 came to $91 million, down 8%. Across the first nine months of 2026, it collapsed to $7 million from a much higher base — a 91% drop — as capital expenditure climbed 56% to $157 million. Lime is spending to grow.
For Q4, Lime expects revenue of $240 million to $250 million and Adjusted EBITDA of $43 million to $45 million. Full-year revenue is guided to $1.04 billion–$1.1 billion, with capex of $172 million–$177 million.
CFO Ann Gugino told analysts that European competitive pressure should persist through the rest of FY2026. Lime is countering with heavier Q4 investment in local fleet management and technology — including sidewalk riding detection and parking verification.
Photo: Lime / Mikro-mobilite Sektörü (Zag Daily) · Official Press Kit / Editorial (Editorial / Press Kit)
Source: Mikro-mobilite Sektörü (Zag Daily)
What do you think?