China's NEV Retail Sales Set to Slip 16.5% in October as Peak Season Fizzles
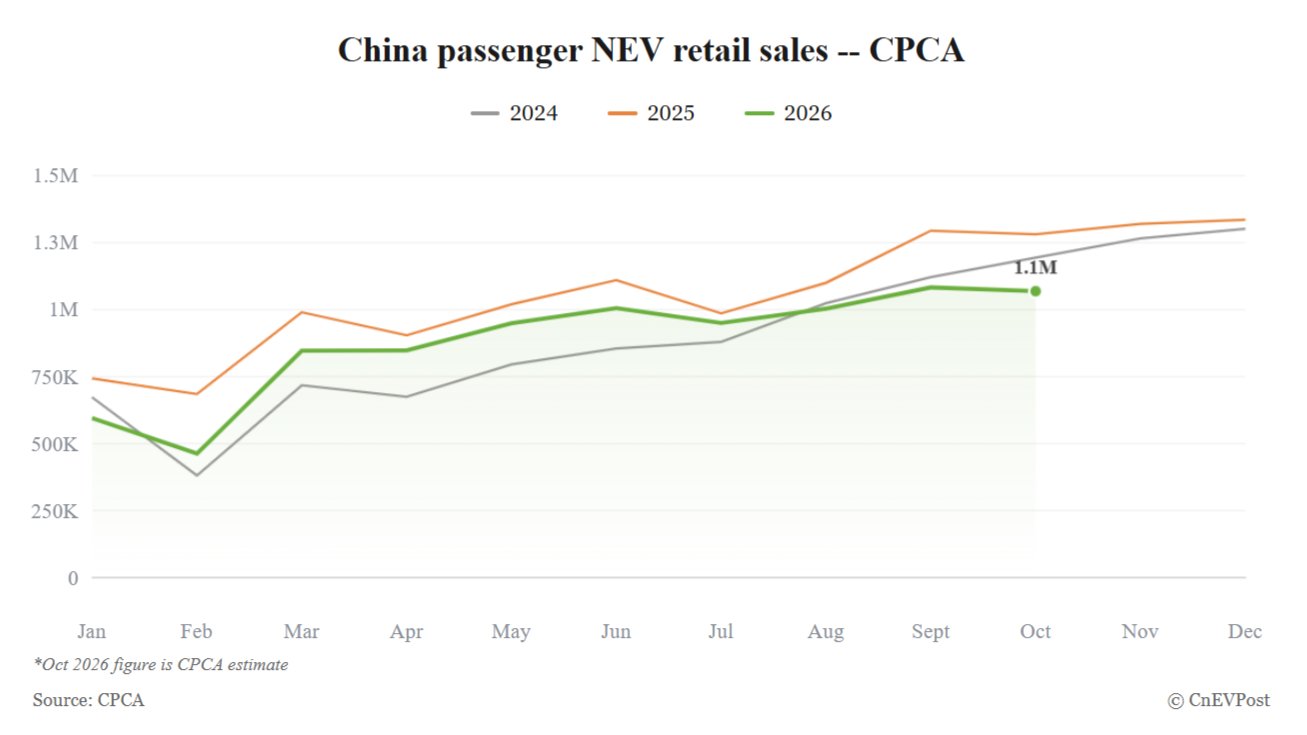
China’s new energy vehicle retail market is heading for a cooler October than anyone had hoped. The China Passenger Car Association (CPCA) now expects NEV retail sales of roughly 1.07 million units for the month — a 16.5% drop year-on-year and a slight 1.3% retreat from September.
The broader passenger car picture looks even rougher. CPCA forecasts total retail volume of about 1.6 million, which would be 28.9% below October 2025 and 1.1% under September — deepening the 28.0% annual fall recorded the month before.
Key Figures: ~1.07 million NEV retail units · −16.5% YoY · 66.9% NEV penetration · 1.6 million total passenger car retail · −28.9% YoY
Penetration Holds, Demand Doesn’t
There is one number the CPCA can point to with some pride: NEV penetration is projected at 66.9%, just a hair under September’s all-time high of 67.0%. Electrified models now dominate Chinese showrooms by sheer share.
But share is not the same as growth. September’s NEV retail sales already slid 16.7% year-on-year — the ninth straight monthly decline — and the first nine months of 2026 closed at 7.758 million units, down 12.8%.
A Holiday Bump That Didn’t Last
The National Day holiday in early October did bring a brief lift in showroom visits. It faded fast. CPCA data shows average daily retail sales climbing to about 58,000 in the second week before sagging to roughly 47,000 in the third.
For the final stretch of the month, the association sees a modest recovery to around 49,000 per day in week four, then a month-end push toward 79,000 in week five. That assumes deliveries of models launched in Q3 settle into a steadier rhythm.
Automakers Wary, Discounts Constrained
Behind the soft numbers sits a cautious industry. Most major manufacturers had cleared less than 60% of their annual targets through three quarters, and an early-October CPCA survey found leadership broadly hesitant about Q4 momentum.
The usual lever — price cuts — is largely off the table. Ongoing efforts to curb excessive competition and protect dealer margins have narrowed the room for aggressive discounting, pushing brands toward conservative inventory planning instead.
A separate CPCA reading for October 1–18 showed 520,000 NEV retail units, down 13% year-on-year, with penetration at 65.9%. Household income expectations remain weak, and buyers are still playing a waiting game as dealers jostle on price.
Gasoline Under Pressure, NEVs at a Plateau
On the internal combustion side, high fuel prices continue to squeeze demand. NEVs, by comparison, are holding steadier — but the growth curve has flattened, and the CPCA’s own framing is blunt: the wider passenger car market is still hunting for a floor.
Several new models are still slated for launch before the year ends, though longer gaps between debut, pre-sale and actual delivery are stretching wait times and testing buyer patience. For now, high penetration is doing the heavy lifting while volume growth stalls.
Source: CnEVPost
What do you think?