
CATL Still Tops China's EV Battery Charts, but BYD Is Closing the Gap for a Fourth Straight Month
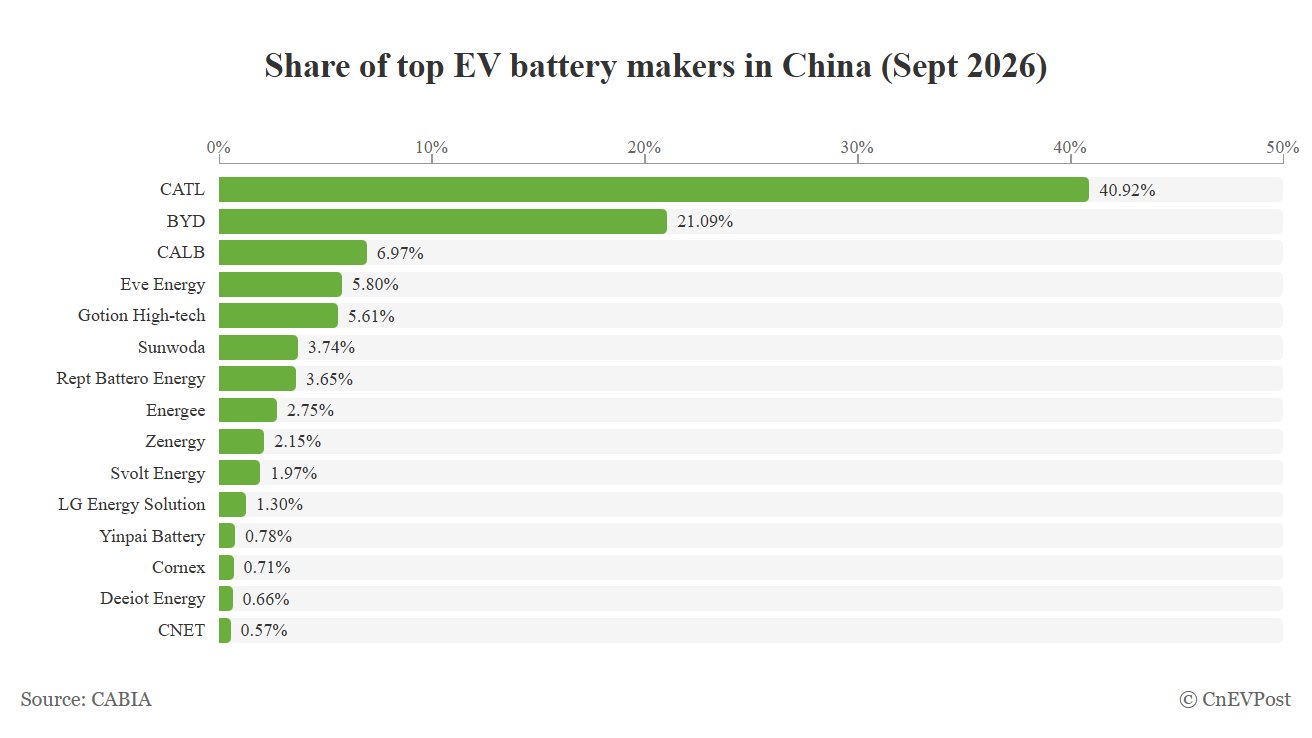
China’s EV battery sector posted another record-setting month in September 2026, yet the headline story belongs to the shifting balance at the very top. According to figures from the China Automotive Battery Innovation Alliance (CABIA), total domestic installations hit 87.2 GWh — a yearly high for the second month running, representing a 14.7% jump year-on-year and a 10.4% gain over August.
CATL (HKEX: 3750) remains the undisputed leader, fitting 35.49 GWh of batteries into vehicles during the month for a 40.92% share. That was roughly 9.1% more capacity than its August tally of 32.54 GWh, but the growth trailed the market as a whole, so its slice of the pie shrank by 0.52 percentage points. BYD (HKEX: 1211), meanwhile, installed 18.29 GWh — an 11.1% month-on-month increase — lifting its share marginally to 21.09%. The margin between the two now stands at 19.83 points, down from 20.47 a month earlier, the fourth consecutive month the gap has narrowed. Together they supplied 62.01% of all batteries installed, slightly less than August’s 62.43%.
Behind the duopoly, CALB (HKEX: 3931) solidified its hold on third, growing installs to 6.04 GWh for a 6.97% share, up 0.46 points. Eve Energy and Gotion High-tech held fourth and fifth with 5.03 GWh and 4.87 GWh respectively, though both saw their shares ease. Sunwoda climbed into sixth, overtaking Rept Battero Energy, while Energee edged ahead of Zenergy to take eighth. LG Energy Solution stayed eleventh overall but its volumes slid to 1.13 GWh, taking its share down to 1.30%. The top five collectively controlled 80.39% of the market, a touch below August.
Chemistry trends underscore where the market is heading. LFP packs dominated with 74.5 GWh installed — 85.5% of the total and up 19.9% year-on-year — while ternary batteries accounted for just 12.3 GWh despite a 11.7% monthly rebound. In the ternary segment CATL commanded 67.78% on 8.34 GWh, and CALB jumped from fifth to second with an 11.23% share (1.38 GWh), displacing LG Energy Solution, which fell to 9.16%. In LFP, CATL’s 27.15 GWh gave it 36.48%, ahead of BYD’s 24.58%; the gap between them narrowed from 12.90 to 11.90 points, and every battery BYD installed at home was LFP.
Year-to-date totals reflect the same pecking order with one notable twist. Cumulative installations across the first nine months reached 576.3 GWh, up 16.7% year-on-year. CATL’s share climbed 1.41 points to 44.16% on 253.68 GWh, while BYD stood at 18.53% on 106.44 GWh — a 4.04-point decline from a year earlier. CALB, Gotion and Eve Energy filled out the top five over the nine-month stretch.
Source: CnEVPost - Battery
Curious how this compares to other EVs? Try our comparison tool →What do you think?